
Winning a new project is always exciting. Whether you're bidding on a commercial contract, municipal project, or private development, contractor insurance compliance should be part of the conversation before timelines, staffing, materials, and mobilization begin.
But before accepting a new job, contractors should take one important step that can help avoid delays later: reviewing the project's insurance requirements, contract obligations, and contractor insurance compliance needs.
Many contractors don't discover insurance compliance issues until work is already underway or payment is being processed. At that point, project owners or general contractors may request additional documentation, endorsements, or Certificates of Insurance that were not reviewed during the bidding process.
Taking time to review insurance requirements before accepting a job can help support a smoother project experience, reduce administrative challenges, and avoid unexpected delays, costs, and compliance issues later in the project.
What is Contractor Insurance Compliance?
Contractor insurance compliance refers to meeting the insurance requirements outlined in a project's contract or agreement.
Because every project is different, project owners, municipalities, general contractors, and property managers may require insurance provisions that differ from those on previous jobs.
Common requirements may include:
-
Additional insured endorsements
-
Waivers of subrogation
-
Primary and non-contributory wording
-
Specific liability limits
-
Project-specific insurance requirements
-
Higher Limits
Because project requirements can vary from one job to the next, reviewing them before accepting a contract can help identify potential coverage considerations, endorsement requests, or documentation gaps early in the process. Working with an advisor to review your contractor insurance coverage can help identify potential requirements before work begins.
The Cost of Finding Out Too Late
Many contractors focus on winning the job, mobilizing crews, and keeping projects on schedule. Problems can arise, however, when insurance requirements are not reviewed until later in the project.
A project owner, municipality, property manager, or general contractor may require specific endorsements, higher coverage limits, or additional documentation before granting jobsite access, processing paperwork, or releasing payment.
Even when those requirements can be addressed, resolving them after work has already started can delay jobsite access, project paperwork, or payment while the necessary documentation is completed. In some cases, policy changes may also be required, which can increase your premium.
A Real-World Contractor Scenario
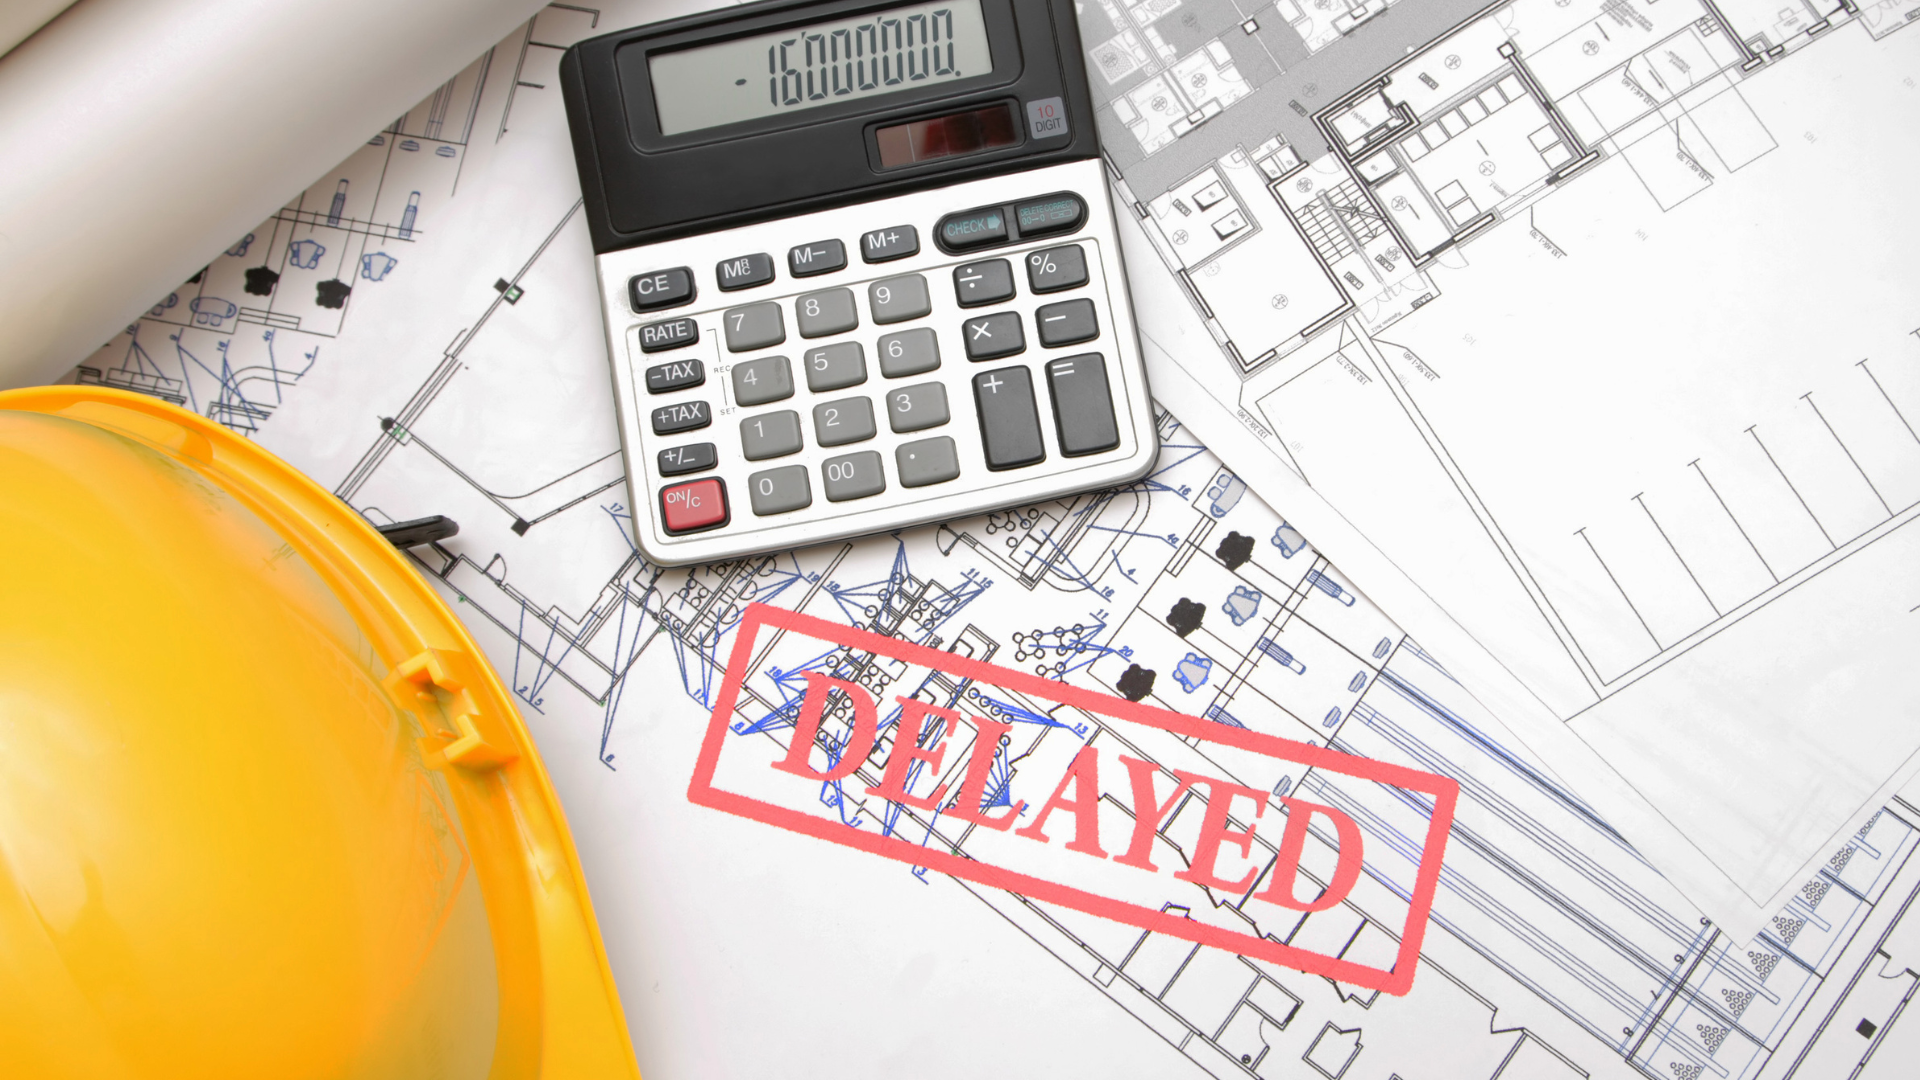
Imagine a contractor who is awarded a renovation project and immediately schedules crews to begin work.
Several weeks later, the project owner requests proof of additional insured status and specific policy endorsements before processing payment. The contractor must now work with their insurance advisor to secure the required documentation while payment is delayed and project paperwork remains incomplete.
Situations like this are one reason many contractors make insurance review part of their pre-project process.
Why Insurance Requirements Should Be Reviewed Before Bidding
Insurance requirements can affect more than compliance. They can also affect project profitability.
Certain contracts may require additional endorsements, higher limits, or specialized coverages that should be evaluated before a proposal is submitted. If these requirements are identified after the job has been awarded, contractors may find themselves managing expenses and administrative requirements that were not considered during the bidding process.
Reviewing requirements early can help contractors:
- Better understand contractual obligations
- Account for insurance-related costs when pricing a project
- Avoid last-minute compliance issues
- Support a smoother project onboarding process
- Strengthen communication with project owners and general contractors
For example, a contractor may submit a bid assuming their existing insurance program meets project requirements. If the contract later requires higher liability limits or additional endorsements, those costs may need to be absorbed if they were not factored into the original bid.
Taking these steps before submitting a bid can help contractors make informed business decisions and prepare for potential insurance and contractual obligations. Contractors working on larger projects may face more complex insurance requirements that should be evaluated as part of their overall construction insurance program.
Certificates Of Insurance (COIs) and Contractor Insurance Compliance
Many project owners, municipalities, general contractors, and property managers require a Certificate of Insurance (COI) before work begins.
A COI provides evidence that insurance coverage is in place and may be required before granting jobsite access, processing project documentation, or releasing payment.
Reviewing these requirements early provides time to address requests before they become urgent.
A Simple Best Practice
Before signing a contract or mobilizing equipment and personnel, send the contract and project information to your insurance advisor.
Doing so allows time to:
- Review insurance requirements
- Confirm compliance obligations
- Identify potential coverage considerations
- Request necessary endorsements
- Issue Certificates of Insurance when needed
This simple step can help avoid unnecessary delays and support a more efficient project start.
Make Insurance Compliance Part of Your Process
Making contractor insurance compliance part of your standard project review process can help identify requirements early, support more accurate planning, and reduce the likelihood of delays once work is underway.
Before accepting a job, review the contract, understand the insurance requirements, and consult your insurance advisor when questions arise. A few minutes spent addressing contractor insurance compliance early may help prevent additional work, unexpected costs, compliance challenges, and payment delays later in the project.
This article is not intended to be exhaustive, nor should any discussion or opinions be construed as legal advice. Readers should contact legal counsel or an insurance professional for appropriate advice.
About the Author