
For many churches across the Gulf states, property insurance has become a much bigger line item in the budget over the past several years.
Higher premiums, larger wind and hail deductibles, tighter underwriting requirements, and fewer carrier options have left some churches with difficult decisions at renewal. In many cases, the goal has become finding available coverage rather than finding the most competitive option.
Fortunately, conditions in the church property insurance market are beginning to shift. More insurers are willing to compete for property coverage, creating opportunities for some churches to revisit their property insurance programs.
If your church property insurance program experienced significant increases over the past five years, now may be a good time to take another look.
What Changing Market Conditions Could Mean for Gulf Coast Churches
Insurance markets move in cycles. Following several years of challenging property conditions, more insurers are now competing for property business, giving churches more options than they may have had in recent years.
That does not mean every church will see a lower premium. Gulf Coast properties remain exposed to hurricanes, wind, hail, flooding, and other severe weather, and insurers continue to look closely at individual property characteristics.
However, churches that have renewed the same program year after year may find that today's options differ from those available even a few years ago.
As the insurance market becomes more competitive, churches that have improved their property may be better positioned to explore new coverage options and potential savings.
Property Improvements Can Help Tell a Better Story
The condition of the property can play an important role in how insurers evaluate church property insurance risks.
Think about what has changed since your church last thoroughly marketed its insurance program.
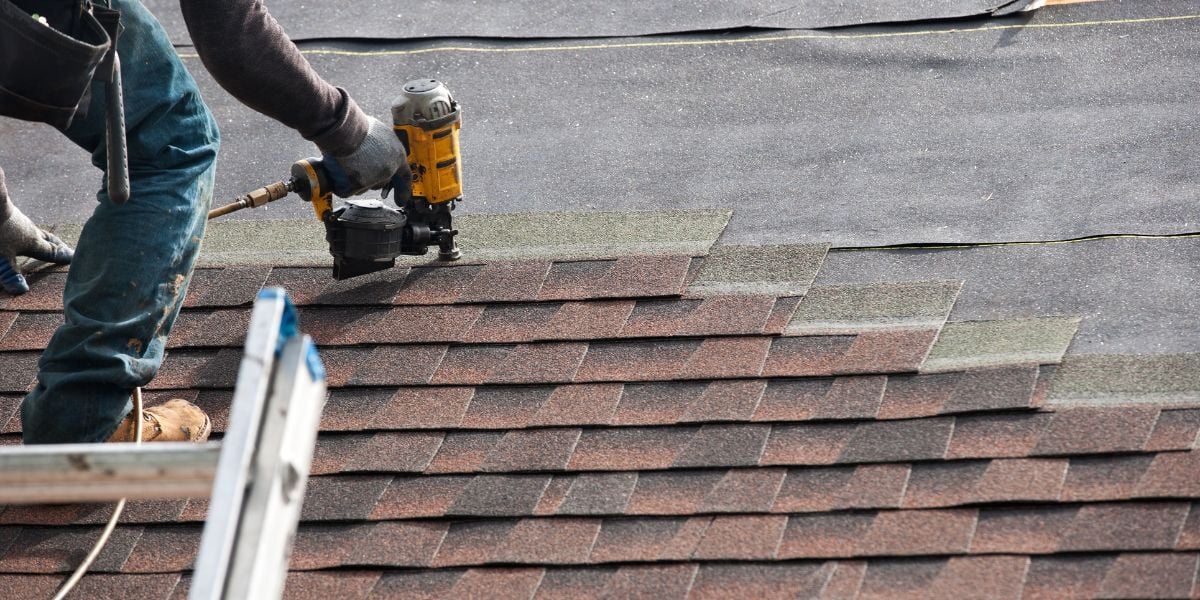
- Has the church replaced or repaired its roof?
- Updated electrical, plumbing, or HVAC systems?
- Installed a monitored fire or security system? Improved drainage?
- Completed storm mitigation projects?
- Kept up with routine maintenance and building repairs?
Insurers want a clear understanding of how a property is built, how it is used, what protections are in place, and what risks it faces. Insurance underwriters often refer to these factors as construction, occupancy, protection, and exposure (COPE). Providing current information about property improvements and steps taken to protect the building can help underwriters get a clearer picture of the property rather than relying on outdated information.
For older churches in particular, documenting upgrades can be important. The age of the building may not change, but many of the systems and features inside it can.
A 40-year-old building with a newer roof, updated electrical system, improved drainage, and documented maintenance presents a different picture than the age of the building alone might suggest.
Look Beyond The Premium
Finding savings does not necessarily mean choosing the lowest-priced policy.
A church should also consider its wind and hail deductible, coverage limits, exclusions, and other policy terms. A lower premium may not provide much value if it comes with a deductible the church would struggle to absorb after a hurricane.
On the other hand, increased competition may create an opportunity to explore not only pricing but also deductibles, limits, and coverage terms. That makes this a good time to review what the church is buying, not just the premium it's paying.
Is It Time to Revisit Your Gulf Coast Church Property Insurance?
Start the conversation early. Gather information about recent property improvements, review your current values and deductibles, and make sure your advisor has an accurate picture of the buildings and protections in place.
The Gulf Coast will always present unique property insurance challenges. However, churches that have not reviewed their property insurance program in several years may have opportunities to explore new options. Changing market conditions, combined with property improvements, may create opportunities to improve terms, strengthen coverage, or identify potential savings.
This article is not intended to be exhaustive, nor should any discussion or opinions be construed as legal advice. Readers should contact legal counsel or an insurance professional for appropriate advice.
About the Author