
Cannabis businesses face many of the same risks as other companies, but the way those risks show up can be very different.
A loss that seems straightforward on the surface can become more complicated when cannabis-specific regulations, specialized equipment, and inventory requirements come into play. That complexity makes it especially important to understand where coverage applies and where potential gaps may exist.
For cannabis business owners, some of the biggest financial exposures can be found in the gaps between what they assume their policy covers and what the policy contract language actually says.
Why Is Cannabis Business Insurance Different?
Few industries have as many different operational touchpoints as cannabis. A product can move from cultivation and processing to manufacturing, testing, distribution, retail, and delivery, with different risks and regulatory requirements emerging along the way.
A cultivator's insurance needs can look very different from those of a dispensary, manufacturer, or delivery operation. That complexity matters when it comes to insurance.
Coverage availability and policy terms can vary by carrier and state, so it's especially important to understand exactly how cannabis-related operations are addressed.
What Are Common Cannabis Insurance Coverage Gaps?
Several exposures deserve a closer look during an insurance review. Below are six common coverage gaps worth discussing with your insurance advisor.
1. Product recalls and contamination: Product liability and product recall insurance serve different purposes. Liability coverage may respond when a product allegedly causes injury or damage, while recall coverage can address certain expenses associated with removing affected products from the market.
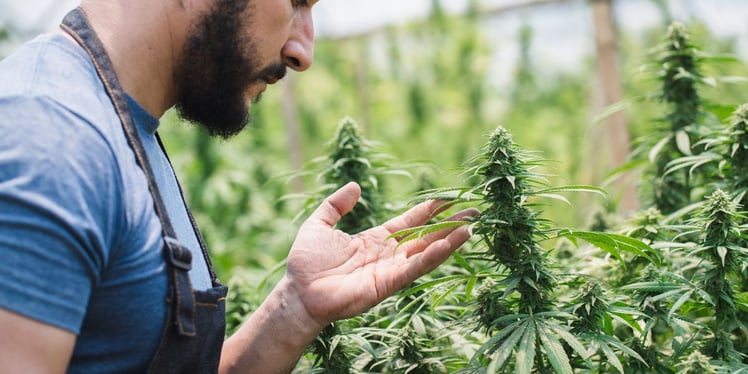
2. Crop and inventory losses: Living plants and harvested inventory can be vulnerable to mold, pests, power outages, and equipment failures. Standard property coverage may not protect living plants or every stage of growth, making it important to understand what is covered and how values are calculated.
3. Equipment breakdown: Cultivation facilities may depend on HVAC systems, grow lights, irrigation, and climate controls. A mechanical or electrical failure can threaten more than the equipment itself; it can also affect crops and interrupt operations.
4. Cash and theft: Cannabis remains a cash-intensive industry for many operators. Coverage limits and security requirements should be reviewed to understand how the policy may respond to theft, employee dishonesty, or cash lost in transit.
5. Cyber incidents: Cannabis businesses increasingly rely on technology for sales, sensitive data, and seed-to-sale tracking. A cyberattack can disrupt operations as well as compromise data, making dedicated cyber coverage an important consideration.
6. Business interruption: A fire, equipment failure, or other covered event can stop production or close a location. Business interruption coverage may help address lost income and certain continuing expenses, but triggers, limits, and waiting periods should be carefully reviewed.
How Can Compliance Affect Cannabis Insurance Risk?
Insurance and compliance are closely connected in the cannabis industry. A regulatory requirement can quickly become an operational and financial issue when something goes wrong.
For example, if testing identifies a problem with a cannabis product, an operator may need to trace the affected inventory, remove product from sale, and document where those products were distributed. What begins as a testing or compliance issue could result in a product recall, lost inventory, and an interruption to normal operations.
Recordkeeping can also become important after a loss. If a cultivation facility experiences property or equipment damage, detailed records of inventory, equipment, and property values can help document what was affected and support the claims process.
Understanding how compliance requirements intersect with day-to-day operations can help cannabis businesses identify potential exposures before a loss occurs.
Why Work with a Cannabis Insurance Specialist?
Cannabis insurance should evolve alongside the business. Adding a delivery service, expanding cultivation, purchasing new equipment, or opening another location can introduce exposures that were not contemplated when the original policy was written.
An insurance advisor familiar with cannabis businesses can help identify potential coverage gaps, explain policy limitations, and evaluate how operational changes may affect insurance needs.
For cannabis business owners, the goal is to understand where the business is exposed before a claim puts the coverage to the test.
This article is not intended to be exhaustive, nor should any discussion or opinions be construed as legal advice. Readers should contact legal counsel or an insurance professional for appropriate advice.
About the Author